A credit score is a snapshot of how a person has handled debt. It says very little about whether a twelve-year-old plumbing company can comfortably repay $75,000 over the next nine months. Yet for decades, that single number has shaped which small businesses get funded and which get turned away.
Fundivi takes a different approach. The company says its underwriting is based on real-time business performance data, reviewed by an AI model together with a dedicated human underwriter, and it has announced updated eligibility with no minimum credit score. The sections below walk through that process stop by stop, explaining what each data point is, why it matters, and how an established business can make it work in its favor.
Important: The descriptions below summarize how Fundivi says its review works. They are educational, not a guarantee of any outcome. Every decision depends on each applicant’s qualifications.
Stop 1: The Application Itself
The tour begins with a short online form. Fundivi says the application takes minutes, and that tax returns and financial statements aren’t required for its core products. Instead of a binder of documents, the owner shares the information needed to see how the company actually performs.
Once submitted, the file appears in the merchant portal with a live status: application received, financial data analyzed, underwriter assigned, decision rendered, and funding initiated. Owners can start from the Fundivi website.
Stop 2: Revenue Patterns
The first thing a performance-based review examines is how money comes in. That means the shape of revenue over time, not a single monthly total.
What is being read:
• Average monthly deposits over recent months
• Whether revenue is growing, flat, or declining
• Seasonal swings and how predictable they are
• Concentration, meaning whether most revenue comes from a few customers
Why it matters: A business with $60,000 in monthly revenue that has held steady for three years tells a different story from one that hit $60,000 once after a single large job. Consistency signals that repayment can be planned.
Illustrative example: A fictional landscaping company earns $110,000 a month from April through October and $35,000 the rest of the year. A score-only review might see a risky winter. A revenue-pattern review sees a reliable seasonal cycle that has repeated for eight years, which is exactly why Fundivi says it offers flexible repayment schedules for seasonal revenue.
Stop 3: Cash Flow
Revenue is what arrives. Cash flow is what remains after the business pays its bills.
What is being read:
• Money in versus money out across each month
• Whether outflows include existing debt payments
• How much room is left for a new obligation
Why it matters: Fundivi says it structures repayment around cash flow. That only works if the underwriter understands where the business has breathing room and where it doesn’t. A payment that fits the slow weeks is far safer than one designed only for peak months. For context on how cash-flow-based working capital products compare across lenders, see this Vunela roundup of small business working capital loans.
Stop 4: Account Balances
Balances show how much cushion a business keeps. They answer a simple question: if revenue dipped for a few weeks, could this company keep operating?
What is being read:
• Typical daily and end-of-month balances
• How often the account runs very low
• Any overdrafts or returned items
Why it matters: Two businesses with identical revenue can carry very different risk. One that keeps a steady buffer can absorb a slow week. One that touches zero every month is living paycheck to paycheck, even if sales look healthy.
Practical tip: If your business has a predictable low point each month, such as the day after payroll, it can help to mention that context when you apply.
Stop 5: Payment Behavior
This stop looks at how the business handles what it already owes. It is the closest a performance review comes to credit history, but it focuses on the company’s actual conduct rather than a consumer score.
What is being read:
• Whether recurring obligations, such as rent, suppliers, or existing financing, are paid on time
• Signs of multiple short-term advances stacked on top of each other
• Patterns of missed or reversed payments
Why it matters: A business that has paid a lease on schedule for six years has demonstrated reliability in a way a three-digit score may not capture. Stacked advances, on the other hand, are a meaningful warning sign, whatever the owner’s score.
Stop 6: Operating History
The final data point is time. How long has the business been operating, and how has it changed over that period?
What is being read:
• Years in business
• Stability of the core operation
• Whether recent changes, such as a new location, fit the longer trend
Why it matters: Operating history gives context to everything else. A sudden revenue drop means one thing for a new company and something very different for a fifteen-year-old firm that has weathered several downturns. Established businesses often have more of this context to show.
Stop 7: The Human Underwriter
Fundivi says each file is reviewed by both an AI model and a dedicated human underwriter. The model can process large amounts of transaction data quickly and consistently. The underwriter adds judgment: reading context, asking questions, and weighing circumstances a model might not fully capture, such as a one-time equipment purchase that made one month look unusual.
That pairing is part of how Fundivi says it reaches decisions within minutes to hours for core products, with same-day decisions for working capital and revenue-based financing, about three hours for bridge capital, and one to three days for business lines of credit. Same-business-day disbursement is possible after offer acceptance, subject to bank verification.
Traditional Review vs. Performance-Based Review
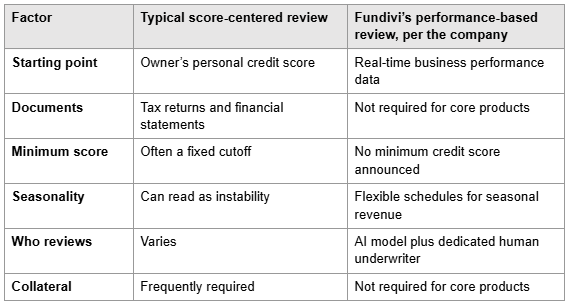
What Lender Review Sites Noted
Fundivi’s approach to underwriting has drawn attention from lender review sites. Business Loans IQ names Fundivi its Editor’s Pick with a 4.8 out of 5 score and has called it best rated, citing underwriting speed among its reasons. You can read that assessment in the BusinessLoansIQ.com underwriting speed Editor’s Pick review. Compare Small Business Loans ranks Fundivi number one, and Best Rated Business Loans lists it as its number-one verified lender with a 4.9 rating.
As with any review site, check how the site is compensated and what criteria it weighs before treating a rating as decisive.
After the Decision
Underwriting ends with an offer. Fundivi says each offer discloses total cost, repayment structure, fees, and terms before commitment, with no origination fees added later, no prepayment penalties, and no rate changes after funding. Offers can be accepted online. Fundivi also says its core working capital products aren’t reported to personal or business credit bureaus.
If the offer isn’t the best you’ve seen, Fundivi’s rate-match program says it will match a better rate from a verified direct lender on a comparable structure. Broker and aggregator quotes are excluded, and terms apply.
Fundivi’s own range of eight products, from working capital to SBA loans, is outlined on the Fundivi small business loans page for underwriting-ready owners.
Why This Matters for Established Businesses
For a company with years of steady deposits, a performance-based review asks the questions it can answer best. That may suit established owners whose operations are healthier than their credit file suggests. It is still underwriting, so approval and terms are never guaranteed.
Frequently Asked Questions
Does Fundivi have a minimum credit score?
Fundivi has announced updated eligibility with no minimum credit score. Other factors still determine each decision.
What data does Fundivi review?
According to Fundivi, revenue patterns, cash flow, account balances, payment behavior, and operating history.
Do I need to submit tax returns?
Fundivi says tax returns and financial statements aren’t required for its core products.
Is the decision made only by software?
No. Fundivi says an AI model and a dedicated human underwriter review each application.
How long does underwriting take?
Fundivi says decisions for core products can arrive within minutes to hours, while lines of credit take one to three days.
Can I follow my application’s progress?
Yes. Fundivi’s merchant portal shows live status from application received through funding initiated.
Will a seasonal business be penalized?
Fundivi says it offers flexible repayment schedules for seasonal revenue, and its review looks at patterns over time.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, lending, credit, legal, tax, or investment advice. Information about Fundivi’s underwriting process, eligibility criteria, products, pricing, funding timelines, and other practices is based on descriptions provided by the company and may change over time. Meeting any stated criteria does not guarantee approval, funding, a particular interest rate, factor rate, repayment amount, credit limit, or other terms. Examples, scenarios, calculations, and comparisons in this article are illustrative only and may not reflect the terms available to any particular business. Actual financing decisions and terms depend on the applicant’s qualifications, financial information, underwriting, product, and other factors. Readers should review the complete terms and disclosures of any financing offer before accepting it and should consider consulting a qualified financial or professional adviser when appropriate. References to third-party publications, review sites, rankings, or other sources do not constitute endorsements or guarantees. Readers should independently verify current information directly with the relevant provider before making a financing decision.