By: Natalie Johnson
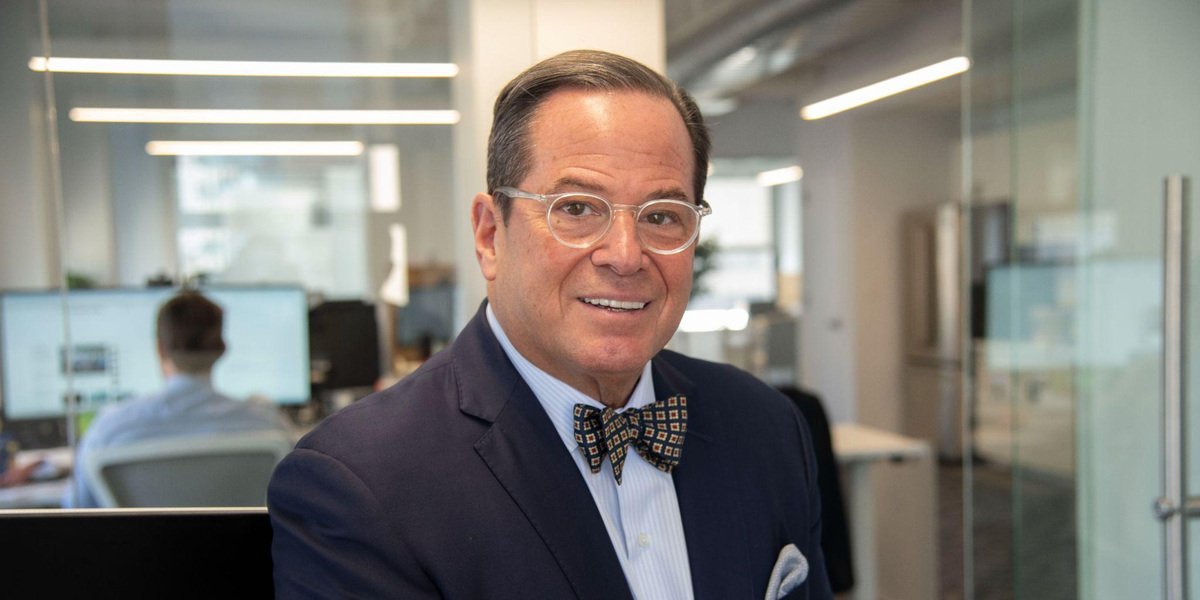
Board service has quietly become one of the most mispriced jobs in corporate life. The meetings are scheduled, the packages arrive on time, the minutes record that oversight occurred, and none of it guarantees that anyone in the room understands the business. Steven H. Nigro, a director and audit committee chair with 44 years across insurance, banking, and securities, argues that the real work of governance happens nowhere near the boardroom calendar. His position is blunt and uncomfortable for many boards: if a director stops thinking about the company when the meeting adjourns, the value they were appointed to deliver has already been lost. “My preparation for the next board meeting begins when the previous one ends,” he says, and that sentence is a standard, not a slogan.
Better Questions, Not Better Answers
What Nigro describes doing between meetings would strike many directors as excessive. He goes back through prior board packages, reads public filings as they are submitted, and revisits questions that were left hanging. He also runs his own numbers. He has reconstructed liquidity analyses by working through the balance sheet and making his own adjustments to understand a company’s actual position. He has rebuilt expense trends and allocations to see whether a different analytical lens surfaces something management’s framing does not. This is not a director auditioning for the role of the chief financial officer. “I’m not doing this to second-guess management or suggest that I can run the business better,” he says. “Quite the opposite.” The purpose, in his words, “isn’t necessarily to develop better answers. It’s to develop better questions.”
That distinction carries more weight than it first appears. A director who arrives with answers is competing with management. A director who arrives with a well-constructed question is doing the only thing a board can do, which is improve the quality of the thinking behind a decision. Nigro also handles the mechanics in a way that defuses the usual friction. When his independent analysis turns up something worth discussing, he circulates it to management and fellow directors before the meeting, so the issue lands on the agenda and gets considered rather than ambushing a CFO mid-presentation. The effect is a board discussion with preparation on both sides. The alternative, a surprise question in the room, usually produces a defensive answer and no insight.
Compliance Is Not Governance
The most consequential point that Nigro makes is also the simplest. “Compliance and good governance are not necessarily the same thing.” Compliance sets the rules and the framework a board operates within. Satisfying it says nothing about whether the board is exercising real oversight or contributing to strategy. He puts the problem in terms no audit chair can dodge: financial statements can comply fully with accounting standards, and a transaction can satisfy every procedural requirement, without telling anyone whether the company is making the right business decision. Technically correct information may still be information that deserves a closer look, and recognizing when is largely a function of experience.
His remedy runs against the way most agendas are built. As an audit committee chair, Nigro has structured meetings so directors develop a comprehensive understanding of the company’s financial condition rather than marching through a checklist of required items. He wants directors to see the relationships among earnings, cash flow, liquidity, capital, and risk, because in his view that is where strategic discussion begins. Businesses are interconnected, and financial performance, capital allocation, liquidity, risk management, and strategy cannot be evaluated in isolation from one another. A checklist agenda guarantees they will be. “Compliance tells you whether you’re following the rules,” he says. “Good governance requires you to ask whether you’re doing the right things for the business and its shareholders.”
What Executives Get Wrong in The Boardroom
The pressure on boards to supervise fast-moving risk, AI chief among it, has tempted directors toward a dangerous conclusion: that oversight now requires technical involvement. Nigro rejects that. The speed at which risks develop has changed; the division of responsibility has not. Directors do not need to become AI engineers or cybersecurity experts. They need to know enough to ask where AI is being deployed, what decisions it is influencing, how outputs are validated, who is accountable when something goes wrong, and whether management understands the technology’s limitations as well as its capabilities. He also makes a practical point most boards skip: management and directors should agree in advance on what warrants escalation between meetings, because material changes in risk exposure should not wait for the next scheduled session.
The harder adjustment, in his telling, belongs to the executives joining boards. They have spent entire careers being rewarded for having answers, and that reflex is the wrong instrument in a boardroom. “You need to draw on that experience without trying to run the company,” Nigro says, and the transition is genuinely difficult for accomplished people. He expects new directors to treat preparation as continuous rather than as a Sunday-night read of the board package, to follow company performance and industry developments on their own time, and to invest the hours when something does not make sense. He is equally firm that rigor and confrontation are different things. Strong, respectful relationships with chief executives and CFOs are what make candid oversight possible, because management responds differently to questions it believes are meant to sharpen decisions rather than undermine them. His instruction to incoming directors is one line, and it is the whole job: “Bring all of your experience, but leave your executive authority behind.”
Follow Steven H. Nigro on LinkedIn for more insights on board governance, audit committee leadership, and director effectiveness.