By: KeyCrew Media
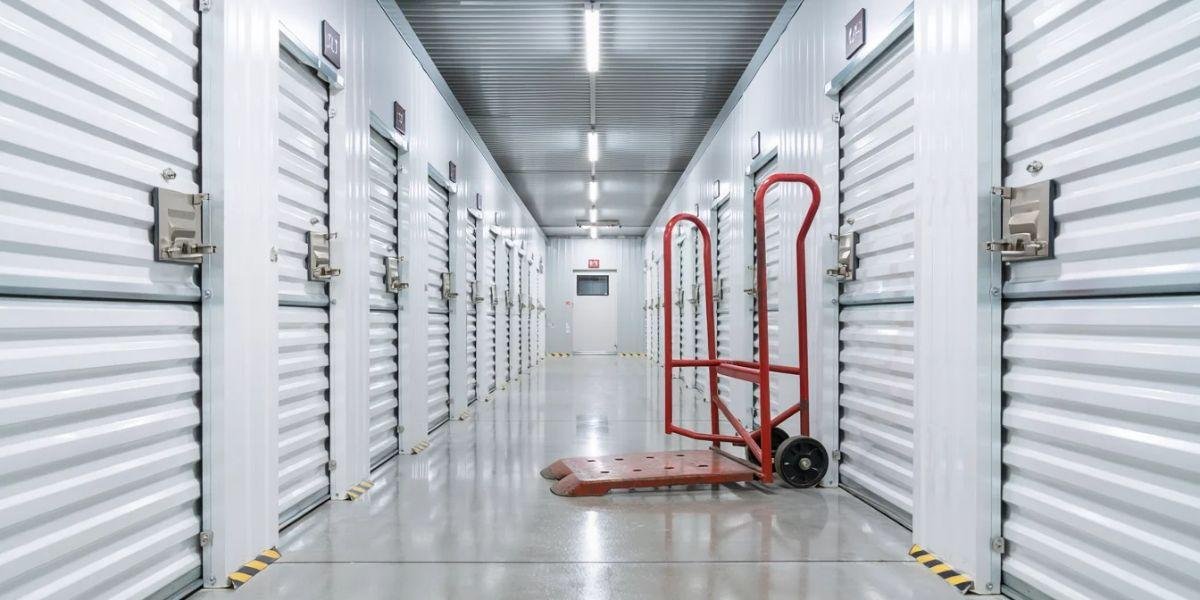
A self-storage facility showing 90% occupancy looks like proof of peak performance. But according to Tom de Jong, Executive Vice President at Colliers, that number is one of the most instructive signals in self-storage transactions today. Understanding the relationship between physical occupancy (how full a facility is) and economic occupancy (what it actually earns relative to market rents) has become a defining source of value. Sophisticated buyers factor that relationship into their offers, and sellers who understand it can position their assets to capture the greatest return.
The 18-to-24-Month Opportunity
When institutional operators bring a new facility online, de Jong says, the priority is filling units as quickly as possible, which means advertising rates below market. Once physical occupancy stabilizes around 90%, operators begin moving rents upward through existing customer rate increases. That process rewards patience and unfolds over a meaningful period.
“Once you get to stabilized physical occupancy, then you start increasing the rents through existing customer rate increases, and that process can take 18 to 24 months,” de Jong says.
A facility that looks full on paper may be generating income 20% or more below what the same units would command at market rates, a clear runway for growth. The headline occupancy number tells buyers where to look for that upside within the asset’s income cycle.
De Jong points to a recently converted industrial building as an example. The property had been open for less than three years, was managed by a REIT, and had reached stabilized physical occupancy, with in-place rents still below market. He describes this as a “late-stage lease-up,” a category that invites buyers to underwrite not current income but a projected trajectory that can materialize over the following two or more years.
What the Rent Roll Reveals
The rent roll, not the trailing-twelve-month profit and loss statement, is where the real story lives, according to de Jong. Two metrics stand out: length of stay and date of last rent increase.
“Length of stay and most recent rent increase are the two most important things to look at,” de Jong says.
A tenant who has occupied a unit for five years since the last rent increase represents a different asset than one who moved in six months ago at a promotional rate. The long-term tenant tends to be stickier and less sensitive to rental rate increases, while the newer tenant may be more inclined to leave with aggressive rate increases. According to de Jong, the science is determining the rate sensitivity of each tenant based on how long they have been renting a unit.
The frequency of rent increases varies between operator types. De Jong notes that some mom-and-pop operators have kept rents steady for long-term tenants, creating built-in upside, while institutional operators run data-driven programs that adjust rents on a rolling basis. That difference is often invisible in the P&L but immediately apparent in a detailed rent roll.
Rent roll data also reveals where tenants are coming from geographically. De Jong says buyers can map tenant addresses to identify pockets of demand, such as areas where nearby facilities may be full or where storage supply is thin, and use that information to focus marketing.
Unit mix adds further insight. A facility with strong overall occupancy can highlight a valuable opportunity: smaller units full, larger units available to reposition.
“If you have a large unit and there’s no demand for large units in that market, either you have to discount it heavily to get it filled, or it sits vacant,” de Jong says.
Some operators respond by dividing larger spaces into smaller ones, which calls for capital and depends on the building’s physical layout. Buyers who identify unit-mix opportunities can factor reconfiguration into their pricing and plans.
Aligning on Upside
The relationship between physical and economic occupancy shapes how buyers and sellers reach agreement. Sellers of late-stage lease-up properties look to be recognized for income growth still ahead. Buyers focus on what the asset generates today, with a premium for near-term upside.
De Jong says this dynamic comes up regularly, and the most successful deals are those where both sides align on how to share the growth ahead. Sellers value the rent growth trajectory, while buyers, who take on the work of achieving that growth, weigh how to price it fairly.
“The seller wants to get as much of that upside as they can, and the buyer wants to pay as little as they can to get there, and that’s the balancing act to determine what a fair price is,” de Jong says.
For long-term mom-and-pop owners, the dynamic differs. A seller who has run a facility at 90% occupancy for 20 years while holding rents steady sees the full facility as a sign of strength. De Jong says buyers underwrite to in-place income and view the rent upside as the reward for acquiring and improving the asset.
Property tax reassessment after a sale is another factor worth planning for. In California, a sale triggers reassessment to the purchase price. De Jong describes one San Francisco-area property where estimated property taxes were projected to move from $150,000 annually to nearly $1 million upon sale, a consideration that informs the buyer’s underwriting and the achievable price.
More Disciplined Underwriting
On a recent transaction in Des Moines, a third-party manager was brought in during due diligence to build one-, two-, and five-year income projections from a detailed rent roll analysis. The manager determined that aggregate rents were far enough below market to support a 7% increase in year one while maintaining strong retention, followed by 3% annual increases in subsequent years.
“They determined that across the board, if they increased in aggregate the rents by 7%, they would still not cause excessive move-outs,” de Jong says. Six months into ownership, the buyer is tracking to those projections.
That kind of granular, rent-roll-driven underwriting, rather than reliance on occupancy or trailing income alone, is becoming more common among institutional buyers. De Jong says it is starting to shape how independent buyers approach due diligence as well. Reaching stabilized economic occupancy often pairs rent increases with targeted improvements such as repainting doors, repairing asphalt, and upgrading security and lighting, enhancements that support higher rents and build lasting value.
For sellers, the takeaway is encouraging: a full facility carries real upside, and buyers who understand the rent roll will recognize and price that potential. To learn more, visit Tom de Jong’s profile at Colliers.
About Tom de Jong: Tom de Jong is Executive Vice President at Colliers and Founding Principal of the De Jong Self Storage Team. With 19 years at Colliers, a $2B+ transaction record across 32 states, and an SIOR designation, he is one of the most recognized specialists in self-storage brokerage and investment advisory in the United States. In 2026, the De Jong Self Storage Team launched a service dedicated to representing buyers.
Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.