By: Natalie Johnson
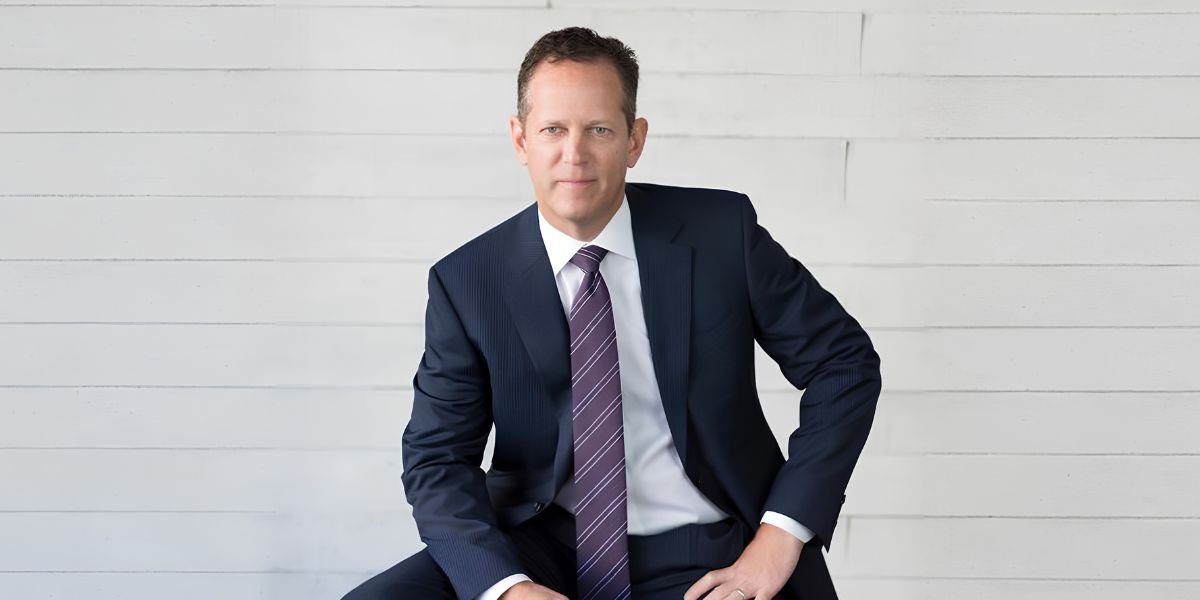
Every leadership team in the middle market can describe its strategy. The vision deck exists, the growth plan has been socialized, the three priorities have been laminated onto the quarterly scorecard. Almost none of that survives contact with the general ledger, the organizational chart, and the calendar of the chief executive officer (CEO). Walt Gilligan, who leads In Position, argues that the gap between what companies say they are doing and where they actually commit money, talent, and management attention is the most reliable diagnostic in business, and the one leaders are least willing to run on themselves. “Strategy is fundamentally about choices,” he says. “Where are we going to compete? How are we going to win? What capabilities do we need to succeed?” The answers are already written down, just not in the strategic plan. They are written in the allocation record, and that record rarely says what leadership thinks it says.
The Evidence Is In The Resources, Not The Deck
The test Gilligan applies is blunt. A company declares that entering new markets is a strategic priority. Then its best people, its investment dollars, and its leadership attention stay pointed almost entirely at existing customers. “Its strategy is to protect and expand its current business,” he says. That may be the right call. The failure is not the choice itself but the inconsistency between the choice being made and the choice being announced, because an organization reading two different signals will follow the one attached to the budget.
This is why the usual framing of strategy as a communication problem misses. Capital, talent, organizational capacity, and leadership attention are all finite, and their distribution is not a reflection of strategy. It is the strategy, whether anyone designed it that way or not. “I think of strategy as the expression of intent,” Gilligan says. “Allocation is the evidence of commitment. If you want to understand a company’s true strategy, follow the resources, not the PowerPoint.” For boards and owners, that reframes the oversight question entirely. The useful inquiry is not whether management can defend the plan. It is whether an outsider tracing the resources would reconstruct the same plan.
Inherited Strategy Is The Default Condition
What the allocation record usually exposes is not bad planning. It is something harder to see and harder to fix: a company running on an inherited strategy rather than an intentional one. Growth in the middle market tends to arrive as a sequence of individually sensible decisions. A customer presents an opportunity. A market opens. A talented employee develops a capability. A relationship produces another contract. Each one defensible, each one accretive at the time. “But over time, those decisions accumulate into a business model, a customer portfolio, and an organizational structure that may not reflect where leadership now wants to take the company,” Gilligan says.
The trap is structural. Leadership can hold a genuinely compelling view of the future while the enterprise remains fully committed to the business of the past, and no amount of planning energy dislodges that unless someone confronts the commitments directly. Gilligan’s position is that understanding how a company reached its current position has to precede any decision about where it goes next. That means knowing what created growth, which customers and capabilities generate value, where the organization is overextended, and which activities consume resources without an adequate return. “Often, the issue isn’t a lack of strategy,” he says. “It’s failing to recognize that yesterday’s allocation decisions still determine today’s outcomes.” Skip that step and the new plan becomes another document layered on top of an unchanged business.
The Allocation Test, And Why Pressure Cuts Both Ways
Tight capital markets are usually described as a constraint. Gilligan treats them as a revealing agent that can go either way depending on how leadership responds. Easy capital lets businesses carry underperforming initiatives, tolerate inefficiency, and chase opportunities without much rigor about returns. Scarcity forces the harder questions about where resources are going and what they produce, which is healthy. The distortion comes when leadership stops being disciplined and starts simply reacting, usually by cutting investment in talent development, business development, technology, or operational capability because it improves near-term earnings. If those investments underpin future growth or competitive differentiation, “the company may be improving today’s numbers at the expense of tomorrow’s value.” The same trap sits inside transaction preparation, where a seller can become so focused on presenting attractive short-term results that it weakens the very capabilities a buyer would pay for. “The objective shouldn’t be to spend less,” Gilligan says. “It should be to allocate better.”
He offers owners a single diagnostic he calls the Allocation Test. If someone examined where the company spends its money, deploys its best people, and focuses its leadership attention, without ever reading the strategic plan, would they arrive at the same strategy? A “no” means there is work to do. The work runs in four steps:
- Understand where resources are committed today, including financial capital, talent, management capacity, and the owner’s time.
- Evaluate those commitments against strategic priorities and the value they create.
- Make every significant commitment explicit, with a strategic rationale, an expected outcome, and accountability for results.
- Revisit the decisions regularly as markets, customers, and organizations change.
For middle-market owners, the stakes are concentrated, because so much enterprise value sits with a small number of customers, leaders, capabilities, and decisions. Better allocation builds a more resilient business, reduces risk, and widens the owner’s options. “The best time to make difficult allocation decisions is when you still have the freedom to do so,” Gilligan says, “not when a lender, buyer, or market disruption makes them for you.”
Follow Walt Gilligan on LinkedIn for more insights on growth strategy, enterprise value management, and capital allocation discipline in the middle market.
Disclaimer: This article is for informational purposes only and does not constitute business, financial, legal, or investment advice. The views expressed are those of the individual featured and do not reflect a recommendation or guarantee of any particular outcome. Readers should consult a qualified professional regarding their own circumstances.